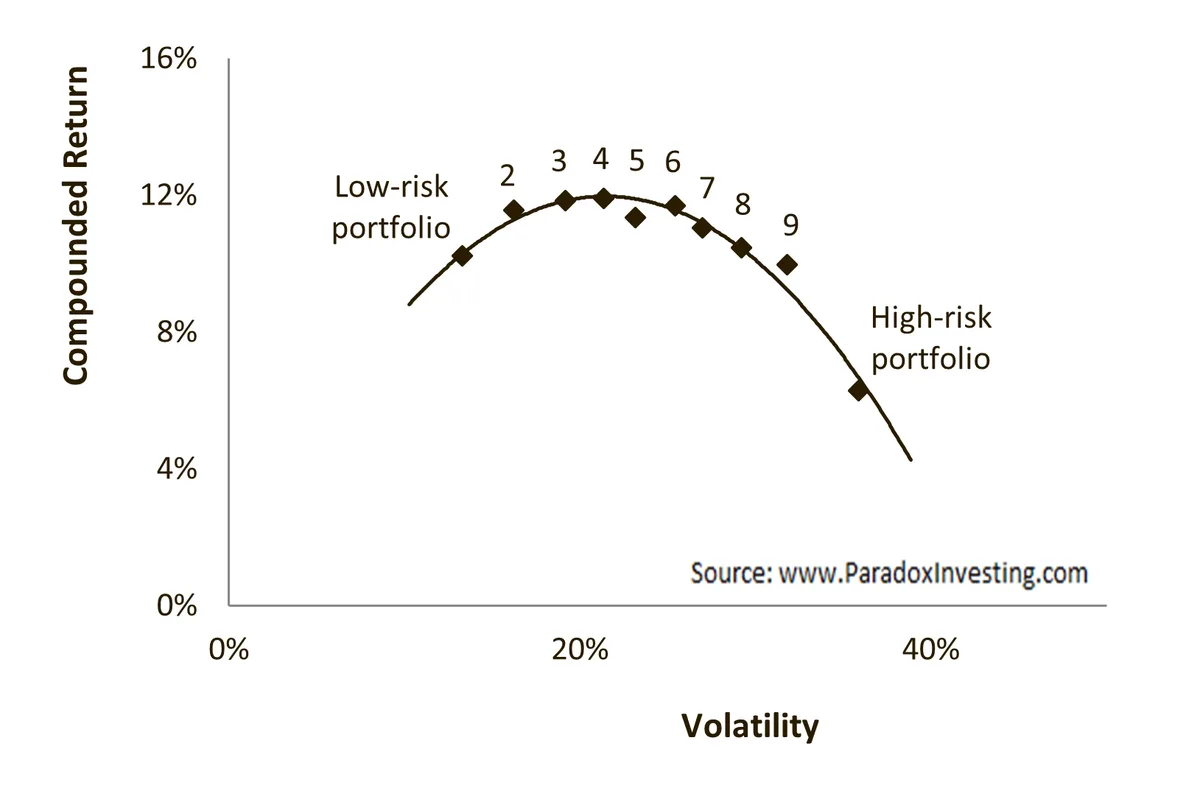
Portfolio rebalancing pulls a drifted allocation back to its target weights, and the research treats it as risk control first, not a return engine. In Vanguard’s November 2015 study, a 50/50 portfolio left untended from 1926 through 2014 ran annualized volatility of 13.2 percent, against 9.9 percent for its annually rebalanced twin.
That finding sets the honest frame. The discipline earns its keep on risk, and it pays for every extra trade along the way. The same rules-first logic runs through this desk’s walkthrough of how professionals analyze a stock before buying, where process beats prediction too.
The figures here come from the Vanguard paper, part of the firm’s research series and archived in full. The authors reduce the machinery to a pair of dials, checking frequency and drift tolerance, plus the small print of how far each reset runs. More allocation work sits on the site’s analysis hub, where these questions get the same evidence-first treatment.
What Does Rebalancing Actually Do to a Portfolio’s Risk?
It caps drift. A rebalanced mix keeps the risk level its owner picked; a neglected one slides toward its hottest asset class. In the 1926 through 2014 test, the untended 50/50 portfolio averaged an 81 percent equity weight and peaked at 97 percent, with volatility of 13.2 percent against 9.9 percent for the rebalanced version. Readers following this should also see Analysis Synonym — Technical vs. Fundamental Analysis: Which School Actually Wins?.
The drift portfolio did post the higher return, 8.9 percent annualized against 8.1 percent. That gap is the equity premium talking, not the method. The study’s forward-looking arm, 10,000 model simulations of 30-year outcomes, had the drift portfolio winning in more than 70 percent of runs, with median volatility of 11.9 percent against 9.2 percent.
Higher return arrived dressed in higher risk. That is the deal rebalancing exists to police. The authors’ own verdict line is blunt: the only clear advantage of the exercise is staying aligned with the target allocation.
Which Trigger Wins the Argument, Calendar or Threshold?
Neither, on the evidence. Vanguard ran time-only, threshold-only, and combined rules over the same 1926 through 2014 mix and found risk-adjusted results essentially indistinguishable across schedules. What moved was the bill. Trade counts, not trigger choice, separated the strategies.
- Time-only: monthly resets logged 1,068 rebalancing events across the 89-year test, against 88 for annual resets, with volatility of 10.1 and 9.9 percent respectively.
- Threshold-only: daily checks with a 10 percent band produced 6 events from 1980 through 2014, while a zero percent band produced 8,826.
- Time-and-threshold: annual checks at a 10 percent band needed 19 events; monthly checks at 1 percent needed 423.
- Never rebalance: zero trades, an 81 percent average equity weight, and the study’s worst volatility reading.
Vanguard’s conclusion lands on the cheap end: annual or semiannual monitoring, paired with 5 percent thresholds, struck a reasonable balance between risk control and cost for broadly diversified stock and bond portfolios. Concentrated or aggressive mixes behave differently, the authors note, and may need tighter watching.
Where Do the Costs of Rebalancing Pile Up First?
Taxes lead the ledger in taxable accounts, because resetting weights means selling winners and realizing gains. Trading frictions follow as commissions and bid-ask spreads. Monitoring labor charges a quieter fee, paid in time or in advisory bills.
The study’s cheapest version used no sales at all. Dividends and interest, swept into the underweight asset class from 1926 through 2014, delivered zero rebalancing events and zero turnover, with volatility of 9.7 percent against 10.1 percent for the monthly zero-threshold version. A monthly check at 5 percent thresholds needed 64 events and 1.6 percent turnover for nearly identical risk.
Vanguard flags the limits of that trick with a candid date range: dividend and yield levels across the 1926 through 2014 stretch may not repeat. Contributions and withdrawals can do the same redirecting job, at the price of some tax planning.
Conclusion: What the Evidence Says Rebalancing Is Worth
Rebalancing buys risk discipline, not extra return. The documented prize is volatility: 13.2 percent for the untended mix against roughly 10 percent for its rebalanced cousins across 1926 through 2014. The documented bill is frequency: 1,068 monthly events against 88 annual ones in the same test. Vanguard’s closing verdict keeps the score even, backing annual or semiannual checks at 5 percent bands as the point where risk control and cost stop fighting. The discipline is real. The drama around it is not.